Its all Insurance
What do I do if my car is written off? | Budget Insurance
 5 min read
Its all Insurance
 September 16, 2026 By Budget Insurance
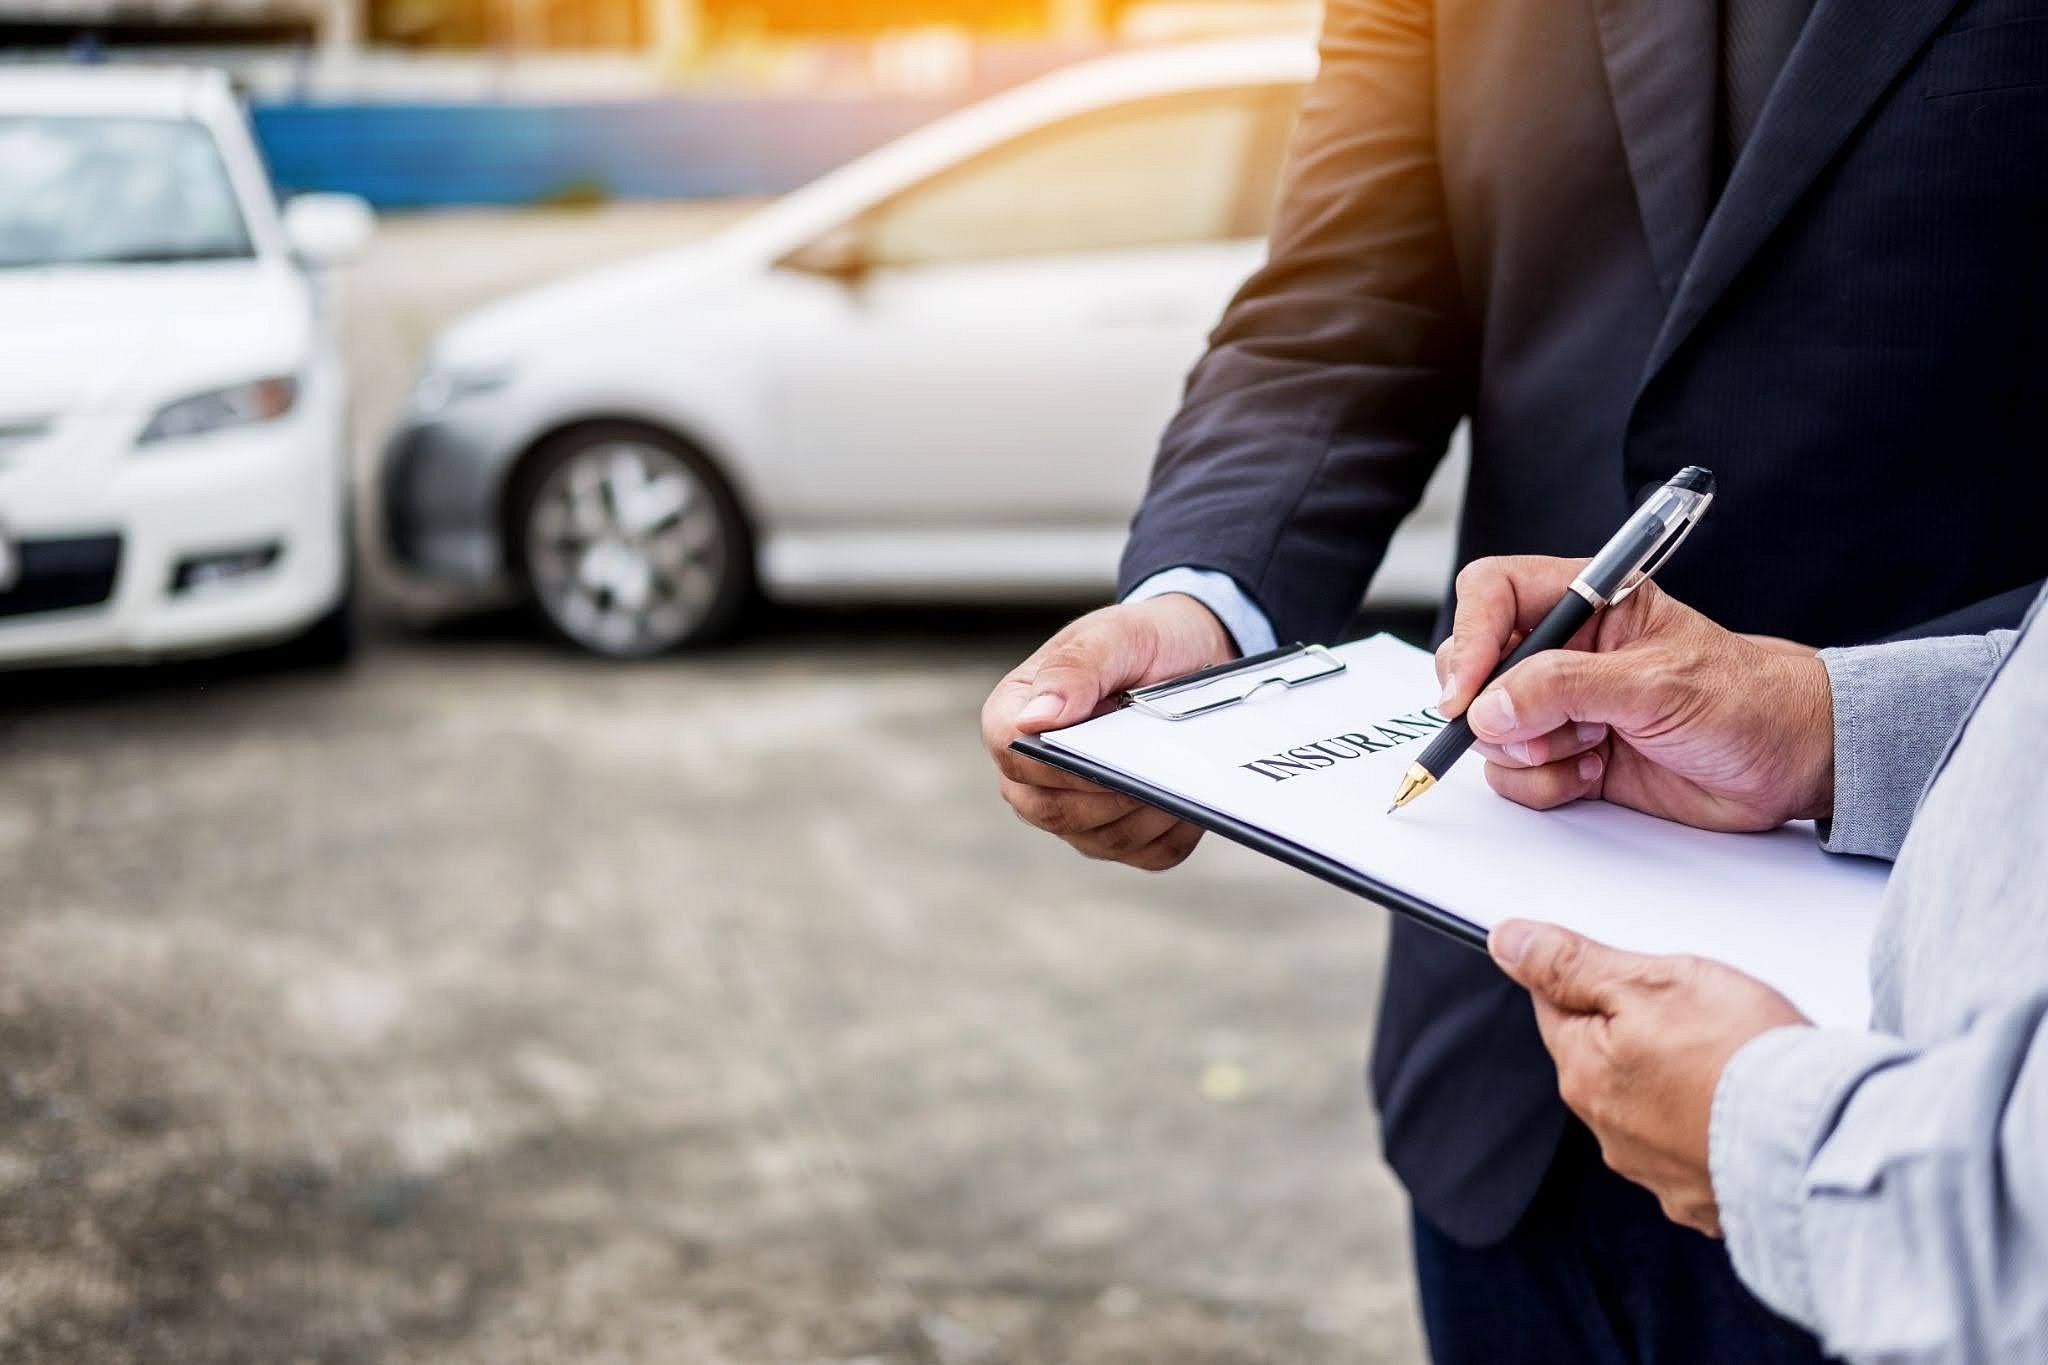
Imagine standing at a busy four-way stop when a vehicle behind fails to brake, smashing into your boot. You step out and ask for the other driver's policy details, only to hear the dreaded words: "I do not have insurance." A cold wave of panic sets in as you wonder who is going to pay the workshop bill to fix your vehicle.
This scenario plays out thousands of times every month across South African suburbs. Many cost-conscious vehicle owners purchase a basic third-party insurance policy, assuming that if someone else causes an accident, the financial burden naturally falls on the guilty party or their financial provider. Unfortunately, relying strictly on minimum liability options creates a major financial recovery roadblock when the responsible driver carries no financial backing. Discover more as Budget Insurance unpacks this issue in more detail.
A basic third-party insurance policy never pays for repairs to your own vehicle, even if an uninsured driver hits you and is entirely at fault. A common misconception among South African vehicle owners is that state funds or statutory bodies assist with repair costs after a road collision.
Under local legislation, the state provides no financial cushion for vehicle damage. According to the official Road Accident Fund Legal Framework, government-backed compensation applies exclusively to bodily injuries or death; the fund explicitly excludes all loss or damage to property, including vehicles. This statutory limitation places the entire burden of vehicle repairs directly onto the involved individuals.
Consider a typical example: Johan, a father from Bloemfontein, maintains a clean driving record and relies on his hatchback for work commutes, school runs and daily errands. While stationary at a traffic light, an uninsured driver hits his rear bumper, causing R28,000 in structural damage.
If Johan carries a basic 3rd party insurance policy, he quickly discovers a tough reality. His policy is built strictly to pay for damage he causes to other people's property. It provides zero financial support to repair his own car, regardless of who caused the collision. Exploring different car insurance types beforehand helps drivers avoid unexpected financial shortfalls.
Holding basic third-party car insurance liability cover while dealing with an uninsured negligent driver severely limits your legal and financial avenues. The 3-step breakdown explains why your third-party insurance policy cannot fix your car and how legal recourse functions under local law.
Firstly, you must immediately gather indisputable evidence at the collision scene to prove the uninsured driver was 100% at fault under South African traffic regulations.
Obtain an official SAPS accident case number at the nearest police station within 24 hours.
Take comprehensive photos and videos showing vehicle positions, point of impact, skid marks, and road signs.
Collect full contact details, national identity numbers, driver licence numbers, and witness statements.
Because your third-party insurance policy excludes own-vehicle damage benefits, your financial provider cannot step in to manage your vehicle repairs.
No insurer recovery: Subrogation is the legal process where an insurer pays for your repairs and then claims that money back from the guilty party. Because your provider paid nothing for your vehicle, they cannot legally initiate subrogation on your behalf.
No claim processing: You cannot submit workshop estimates or damage assessments to your provider for your own vehicle repairs.
Direct financial liability: Towing fees, storage centre costs, and panel beating bills remain your personal financial responsibility.
To recover repair expenses from an uninsured negligent driver, you must pursue civil legal action against them in your personal capacity.
Small Claims Court: For repair bills under R20,000, you can lodge a personal claim through the Small Claims Court without hiring an attorney.
Formal Magistrate Litigation: For damage claims exceeding R20,000, you must issue formal civil court summonses through a legal practitioner.
Legal Guidance: Policyholders with Budget Legal Insurance can access professional legal advice to draft demand letters and navigate civil recovery against uninsured drivers.
Relying solely on a minimum third-party insurance liability policy leaves your household savings exposed to sudden, unmanageable workshop bills. Thankfully, budget-conscious drivers can take proactive steps to secure complete peace of mind.
While holding 3rd party insurance shields you against costly financial claims if you damage a luxury vehicle, upgrading provides total asset safety. By selecting Budget’s Comprehensive Car Insurance, you are guaranteed vehicle repairs are settled directly by your provider, even if the negligent driver is uninsured. Your provider then handles all legal recovery efforts against the guilty party in the background.
While third-party car insurance offers an attractive low-entry premium, comprehensive car insurance is often the more economical choice in the long run. For families balancing tight monthly expenses, a single major collision with an uninsured driver can wipe out emergency savings or leave you without transportation altogether.
Comprehensive insurance eliminates this vulnerability by funding vehicle repairs, replacement costs, and legal recovery efforts upfront. Budget-conscious drivers can keep monthly premiums highly manageable by choosing a slightly higher voluntary excess or utilising tools like the Budget Car Insurance Calculator to customise a policy structure that fits their monthly limit.
No. Basic third-party car insurance policies only pay for damage you cause to other people's property. They never fund repairs to your own vehicle, even when an uninsured driver is entirely at fault.
Insurers only pursue legal recovery (subrogation) when they have paid out a claim for your repairs. Since basic liability policies do not pay for your vehicle, insurers cannot legally claim on your behalf.
You must pursue civil legal action directly against the driver. Claims under R20,000 can be lodged via the Small Claims Court, while larger claims require private civil court proceedings.
No. Vehicle insurance is not legally mandatory in South Africa. This absence of compulsory road insurance makes carrying proper financial backing essential for all local drivers.
Comprehensive cover pays for your vehicle's repairs upfront following an accident, theft, or weather event. Basic third-party insurance only pays for damage you cause to third-party property.
Understanding policy limits allows vehicle owners to avoid severe financial surprises after a crash. While maintaining 3rd-party insurance provides vital liability risk mitigation, upgrading to comprehensive car insurance cover guarantees complete financial safety against uninsured drivers. Secure your family vehicle today without overstretching your household finances. Get a quick, accurate car insurance quote online today.
—------------------------------------------------------------------------------------------------------------------
Sources:
Road Accident Fund: The Legal Framework
Disclaimer: The information in this article is provided for informational purposes only and should not be construed as financial, legal, or medical advice. Insurance products, warranties, service plans, and maintenance plans are subject to terms, conditions, exclusions, limits, and eligibility criteria, and are offered separately. Budget Insurance is a licensed non‑life insurer and authorised FSP. Ts & Cs apply and are available online”
 5 min read
